Interest rates set your monthly principal-and-interest payment, and that payment sets the price you can qualify for. Freddie Mac reported a national 30-year average of 7.40% on October 8, 2026. At Orange County prices, budget around the monthly payment, confirm your lock terms, and check county assistance before you shop.
How do interest rates affect first-time buyers in Orange County?
Interest rates set your monthly principal-and-interest payment, and that payment decides how much home you can qualify for. Freddie Mac reported a national 30-year fixed average of 7.40% on October 8, 2026, and Orange County's median listing price was $1,287,500 in September, so even a small rate move changes your budget. For Home Buyers in Orange County, the smart approach is to budget the payment rather than the price, and to confirm your numbers on a lender's written loan estimate.
Key Takeaways
The national 30-year fixed mortgage rate averaged 7.40% on October 8, 2026, and the 15-year averaged 6.73%, according to Freddie Mac.
Orange County's median listing price was $1,287,500 in September 2026, down from $1,349,500 in July, which shows how fast the price you are shopping against can move.
A rate change affects principal and interest only; property taxes, insurance, mortgage insurance, and HOA dues have to be budgeted separately.
The County of Orange Mortgage Assistance Program offers deferred down-payment loans of up to $120,000 or $80,000 depending on income, but it requires homebuyer education, counseling, and a participating lender.
Nobody times rates reliably, so the right question is whether you can carry the payment comfortably today.
I have walked many buyers through their first purchase in Orange County, and the rate conversation is where most of them feel the most pressure. Rates are the one number you can't negotiate with a seller, but you can plan around them. Here is how I break it down for the Home Buyers in Orange County who sit down with me.
How Do Interest Rates Change What Home Buyers in Orange County Can Afford?
A higher rate raises the principal-and-interest payment on the same loan amount, so at a fixed monthly budget you qualify for a lower price. When rates fall, the reverse is true. In a high-price market like ours, that effect shows up fast because the loan amounts are large.
What moves with the rate, and what doesn't?
Only part of your housing payment responds to the rate. Mixing these together is the most common budgeting mistake I see.
Rate-sensitive: principal and interest, which change with the loan amount and the interest rate.
Not rate-sensitive: property taxes, homeowners insurance, mortgage insurance, HOA dues, maintenance, and utilities.
Evaluate the second group on its own line items. A lower rate won't fix a high HOA due, and a high rate doesn't change your property tax bill.
Where do rates stand right now?
The most recent Freddie Mac survey, dated October 8, 2026, put the national 30-year fixed average at 7.40% and the 15-year at 6.73%. Both come from the Freddie Mac Primary Mortgage Market Survey. These are national benchmarks, not a quote for you. Your actual offer depends on your credit profile, loan type, down payment, points, and lender. A 15-year loan usually costs less in total interest but requires a higher monthly payment than a 30-year loan.
What does local pricing look like?
A Federal Reserve Bank of St. Louis series shows Orange County's median listing price at $1,349,500 in July 2026, $1,299,000 in August, and $1,287,500 in September. That is a listing-price measure, not a closed-sale price and not a first-time-buyer price point. The takeaway is that both prices and rates shift, and your payment responds to both.
For closed sales, recent local market data across several of the areas I serve looks like this (trailing 90 days):
Orange County Market - Comparison - Trailing 90 Days
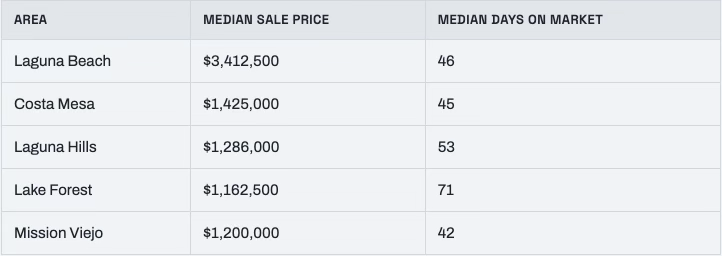
Orange County real estate market comparison showing median sale prices and median days on market for Laguna Beach, Costa Mesa, Laguna Hills, Lake Forest, and Mission Viejo over the trailing 90 days.
These are area-level medians, and an individual home's value depends on condition, street, build year, and timing. The Laguna Beach figure reflects the wider coastal market and is not a price expectation for any particular home. For the broader picture, the Orange County REALTORS® market data page publishes CRMLS-based snapshots for attached and detached homes.
What does a one-point rate change do to your payment on a specific price? It depends on your loan amount, your down payment, and your loan type. That is exactly the scenario I run for clients before they ever tour a home.
How Should You Budget When Rates Keep Moving?
Build your budget around a monthly payment you can carry comfortably, then work backward to a price. Starting from a price and hoping the rate cooperates is how buyers end up stretched.
Start with the payment, not the price
Decide the total monthly housing number you can sustain, including taxes, insurance, and any HOA dues.
Ask your lender for a written loan estimate at today's rate, then ask for the same estimate at a higher rate.
Shop only inside the range that still works in the higher-rate scenario.
If you are buying with a partner, agree on that number together first. My post on tips for couples buying their first home together covers how to have that conversation.
Get the rate-lock details in writing
A rate lock is time-sensitive. Before you rely on any payment estimate, confirm the lock period, the extension terms, the expiration date, and what happens if you need to change the locked rate. I won't quote a universal lock length or fee here because they vary by lender and loan, and they should come from a specific loan estimate.
Check county down-payment assistance early
The County of Orange Mortgage Assistance Program offers up to $120,000 in deferred down-payment assistance for qualifying low-income first-time buyers and up to $80,000 for qualifying moderate-income buyers. The county describes these as 30-year, 3% simple-interest, deferred-payment loans.
Here is what the program requires:
A minimum 1% buyer contribution
Primary-residence occupancy
A HUD-certified homebuyer education workshop and a one-on-one housing counseling session
A participating lender
A purchase price no higher than 85% of the Orange County median sales price for all homes
The county's published 2026 income limits vary by household size. For example, the 80%-of-area-median limit is $104,200 for a one-person household and $148,850 for a four-person household. The limits and rules can change, so verify the current program year with the county. Because the assistance is a deferred loan rather than a grant, review the repayment, lien, occupancy, resale, and refinancing conditions with the program administrator and your lender. Also build the education and counseling steps into your timeline, since they have to happen before you proceed.
For a broader explanation, see my post on how down payment assistance programs work. If you are still saving, where to keep your down payment savings is worth a read.
Compare loan structures, not just rates
A lower advertised rate isn't always the better deal once points, mortgage insurance, and the loan type are factored in. A VA loan, for example, is priced and structured differently from a conventional loan, and I'm glad to walk you through that comparison if it's an option for you. Which combination works depends on your credit, your down payment, and your goals, so compare full loan estimates side by side.
Should You Buy Now or Wait for Rates to Fall?
Buy when you can carry the payment comfortably and plan to stay long enough to make the purchase worthwhile; don't try to guess the bottom of the rate cycle. Nobody times rates reliably, and waiting has its own cost, because prices and inventory move too.
If rates drop later, you may be able to refinance, but that is not guaranteed. It depends on the rate available then, your credit, your equity, the costs of the new loan, and any conditions attached to assistance programs. Treat a future refinance as a possible bonus, not as part of the plan that makes today's payment work.
One timing note: with winter approaching, buying in the off-season can work in your favor because there is typically less competition and some sellers are more motivated. I explain why in my post on buying a home during the off-season.
Every buyer's situation is different, and the only way to know your real number is to run it with someone who knows this market. That is the first meeting I have with every buyer.
FAQ
How much does a 1% mortgage-rate increase change my monthly payment in Orange County?
It raises your principal-and-interest payment by a meaningful amount, and the size depends on your loan amount, term, and down payment. Because Orange County loan amounts are large, the effect is bigger here than in lower-priced markets. I can run your exact scenarios side by side so you see the difference before you make an offer.
Can first-time buyers refinance if mortgage rates decrease later?
Often yes, but it is never guaranteed. Whether a refinance makes sense depends on the new rate, your credit, your home equity, and the cost of the new loan. If you use down-payment assistance, review its lien and refinancing conditions with the program administrator first.
Are there Orange County down-payment-assistance programs for first-time buyers?
Yes. The County of Orange Mortgage Assistance Program offers deferred down-payment loans of up to $120,000 for qualifying low-income buyers and up to $80,000 for qualifying moderate-income buyers. It requires homebuyer education, housing counseling, and a participating lender. Confirm eligibility and current income limits directly with the county.
Can I use down-payment assistance with an FHA, VA, or conventional loan?
It depends on the program and the participating lender. The county program requires you to use a participating lender, so ask which loan types they pair with the assistance before you commit. I can help you compare the options once you know your eligibility.
How much income do I need to buy a home in Orange County at current rates?
There is no single number, because it depends on your debts, down payment, credit, loan type, and the property's taxes and insurance. With the national 30-year average at 7.40% as of October 8, 2026, a lender's preapproval is the only reliable answer. Start there, then we shop within a payment range you are comfortable with.
Rates will keep moving, and your plan should hold up when they do. If you want your payment range, your assistance options, and a realistic search strategy in one conversation, get a free home valuation or search coastal listings with me, and let's map out your purchase.
About Ron Pickett
Ronald “Ron” Pickett is an Orange County luxury Realtor and Dana Point and coastal property expert, verified in the Top 1.5% nationwide by RealTrends (2023, 2025 and 2026). A retired firefighter with nine years of service at MCAS El Toro, he built a background in loan documents and mortgage lending before focusing on real estate and investment properties in Newport Beach and surrounding areas. Ron has lived in Orange County since 1993 and resides in Dana Point.
Coldwell Banker Realty · (949) 246-8500
Equal Housing Opportunity. Ron Pickett, CA DRE # 01379585, Coldwell Banker Realty, CA DRE # 00616212. Regulated by the California Department of Real Estate. This article is general information, not legal, tax, or financial advice; confirm your own numbers with your escrow officer, tax advisor, or lender.