Before you tour a single home in Costa Mesa, get mortgage pre-approval. With a median sale price of $1,423,000 and homes moving in 45 days, sellers expect a letter before they'll take your offer seriously, and pre-approval tells you exactly what you can spend.
Why does pre-approval matter when buying a home in Costa Mesa?
Pre-approval is a lender's written assessment, based on your income, assets, debts, and credit, that it is prepared to lend up to a specified amount. In Costa Mesa, where the median sale price is $1,423,000 and homes average 45 days on market, sellers routinely require a pre-approval letter before they will consider an offer. Getting it done first keeps you competitive and tells you exactly where your budget stands before you fall in love with a property.
Key Takeaways
Costa Mesa's median sale price is $1,423,000, with homes averaging 45 days on market, sellers here expect a pre-approval letter before reviewing any offer.
Pre-approval is not a guaranteed loan offer; the property still must satisfy the lender's appraisal, title, and underwriting requirements before closing.
The Consumer Financial Protection Bureau recommends comparing at least three lenders, terms, rates, and responsiveness vary more than most buyers expect.
Pre-qualification and pre-approval are not standardized terms; always ask your lender exactly what documents and financial information they reviewed.
If you are considering a California assistance program, check CalHFA's eligibility and education requirements before relying on that program in your budget.
Buying a home in Costa Mesa at today's prices is one of the largest financial decisions most people make. Before you start touring properties, or even before you start seriously browsing listings, there is one step that will determine how every other step goes: getting pre-approved for a mortgage. I walk every buyer through this before we ever schedule a showing, and here is exactly why it matters.
If you are still weighing whether now is the right time to buy at all, it helps to work through the five questions to ask yourself before deciding to buy first. Once you are ready to move forward, pre-approval is step one.
What does pre-approval actually involve, and how is it different from pre-qualification?
Pre-approval is a lender's tentative statement that it is willing to lend up to a specified amount, based on a review of your financial picture. According to the Consumer Financial Protection Bureau, it is not a guaranteed loan offer, final approval still depends on further verification, the property's appraisal, title clearance, and underwriting. But it is far more meaningful than a quick online estimate.
Pre-qualification and pre-approval are not standardized terms, and lenders use them differently. The CFPB is direct on this: the level of financial review can vary significantly between lenders. A pre-qualification might be nothing more than a five-minute online form with no document verification. A true pre-approval means the lender has reviewed your income, employment, assets, debts, and credit history.
When you are buying a home in Costa Mesa at this price level, that distinction matters enormously. Always ask your lender: "What documents did you review, and what conditions remain before final approval?" If they can't answer clearly, keep shopping.
What documents will a lender typically ask for?
Expect to provide recent pay stubs, W-2s or tax returns for the past two years, bank and investment account statements, and identification. Self-employed buyers should be prepared to show additional documentation. The lender will also pull your credit report, which I cover below.
What is the difference between your approved loan amount and your actual budget?
This is one of the most important things I tell buyers before we start looking. The lender's maximum loan amount is not a recommendation to spend that much. Your real budget has to account for your down payment, property taxes, homeowner's insurance, any HOA dues, reserves, and all lender-required cash-to-close items. A lender approves you for what they are willing to lend, your comfortable monthly payment may be a different number entirely. Work that out before you tour your first home.
Why pre-approval strengthens your position in the Costa Mesa market
Recent local market data shows 52 new listings in the past 30 days and 178 homes sold over the past 90 days in Costa Mesa. With a median of 45 days on market and a median sale price of $1,423,000, this is not a market where you have weeks to get your paperwork together after finding a home you want. Sellers here are fielding offers from buyers who are ready, and a pre-approval letter is the baseline expectation.
The CFPB puts it plainly: sellers frequently require a pre-approval letter before accepting an offer, because it signals that the buyer is likely to obtain financing. Without one, your offer goes to the bottom of the pile, or gets ignored entirely.
Beyond the competitive angle, pre-approval surfaces problems early. If there is a credit issue, a documentation gap, or a debt-to-income concern, finding out now, before you are under contract, gives you time to correct it. That is a far better situation than discovering it after you have already negotiated a price and are watching a closing date approach.
There are also questions most buyers forget to ask before buying that become much clearer once you have a pre-approval letter in hand and a real budget to work with. I cover several of those in my post on questions most buyers forget to ask before buying.
How does Costa Mesa compare to other Orange County markets?
Here is a current snapshot of median sale prices and days on market across the areas I work. Knowing where Costa Mesa sits relative to other coastal and inland communities helps you understand what your pre-approved budget can reach.
Costa Mesa & Orange County Market Comparison - October 2026
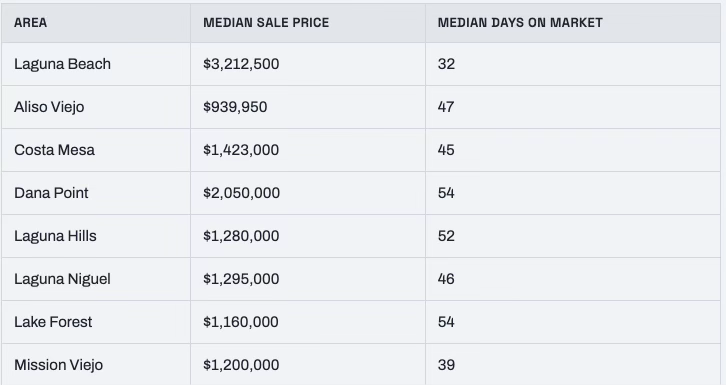
Orange County real estate market comparison showing median sale prices and median days on market for Costa Mesa and seven nearby cities in October 2026.
Source: Aggregated public listing data, trailing ~90 days, as of October 2026. Area-level medians, individual home values vary by condition, street, build year, and timing. Data reported monthly from CRMLS; see Orange County Realtors for current county market reports.
How to approach the pre-approval process in Costa Mesa
Here is the sequence I walk my buyers through:
Review your finances first. Pull your credit reports, tally your debts, and get a clear picture of your savings before you call a single lender. Surprises at the lender's desk slow everything down.
Compare at least three lenders. The CFPB recommends shopping at least three lenders for pre-approval. Loan terms, estimated rates, and lender responsiveness vary, and in a competitive offer situation, a lender who answers the phone matters as much as the rate.
Submit your documentation. Income, employment, assets, debts, and credit. Ask what was reviewed and what conditions remain before final approval.
Receive your letter and understand what it says. It should state the approved loan amount, the loan type where applicable, and any remaining conditions. Keep it time-sensitive in mind, ask when it expires and what changes you need to report.
Set your purchase-price range. Your comfortable budget, not just the lender's maximum. Factor in all the costs beyond the mortgage payment.
Begin focused home tours. Now you are shopping with purpose. Every home you walk through is within reach.
One more thing worth knowing: your pre-approval letter does not commit you to that lender. According to the CFPB, getting pre-approved by a lender does not obligate you to use them for the actual loan. You can still shop and switch, the letter is a tool, not a contract.
What about California assistance programs?
If you are exploring down payment assistance or first-time buyer programs, check CalHFA's homebuyer programs early in the process. CalHFA defines a first-time homebuyer as someone who has not owned and occupied a principal residence during the previous three years, with additional restrictions tied to a spouse's ownership history. Some programs also require completion of a homebuyer education course. Confirm your eligibility and any education requirements before you build a program into your budget, and verify all details directly with a CalHFA-approved lender, since program availability and terms change.
Your specific situation, income, credit, down payment, property type, determines which programs you may qualify for. That is a conversation worth having with both a lender and with me before you start making offers.
Frequently Asked Questions
Do I need a pre-approval letter before touring homes in Costa Mesa?
You are not legally required to have one before touring, but most listing agents in Costa Mesa will ask for it before scheduling a showing on a serious inquiry, and sellers will require it before reviewing any offer. Getting pre-approved before you tour also keeps you focused on homes you can actually buy, which saves everyone time.
What is the difference between mortgage pre-qualification and pre-approval?
Pre-qualification is typically a quick, unverified estimate based on information you self-report; pre-approval involves the lender actually reviewing your income, assets, debts, employment, and credit. The CFPB notes that these terms are not standardized, so always ask your lender exactly what they reviewed and what conditions remain, the label alone tells you very little.
Does getting pre-approved hurt my credit score?
A pre-approval requires a hard credit inquiry, which can cause a small, temporary dip in your score. However, mortgage inquiries made within a short window, typically 14 to 45 days, depending on the scoring model, are usually counted as a single inquiry, so shopping multiple lenders in a focused period has minimal impact. The benefit of knowing your real buying power far outweighs a minor short-term score effect.
How long does a pre-approval letter remain valid?
Most pre-approval letters are valid for 60 to 90 days, though this varies by lender. After that window, the lender will need to re-verify your financial information. More importantly, any significant change in your employment, debt level, credit activity, or assets during that period can affect your approval, report those changes to your lender promptly rather than waiting for the letter to expire.
Should I get pre-approved by more than one lender?
Yes. The CFPB recommends comparing at least three lenders, and I agree, loan terms, rates, and lender responsiveness all vary, and you won't know the difference until you compare. Getting multiple pre-approvals also does not commit you to any one lender; you can still choose based on the full loan estimate when you are ready to move forward.
Buying a home in Costa Mesa at a median of $1,423,000 is not the place to figure out your financing on the fly. Pre-approval is the step that turns a wish list into a real plan, and it is the single biggest thing you can do to protect your position before you make an offer. If you are ready to get started or want a clear picture of what the buying process looks like in this market, reach out and let's map it out together.
About Ron Pickett
Ronald “Ron” Pickett is an Orange County luxury real estate agent with Coldwell Banker Realty, verified in the Top 1.5% Nationwide by RealTrends in 2023, 2025, and 2026. A Dana Point resident since 1993 and a retired USMC firefighter, Ron brings a background in mortgage lending, investment property acquisition, and decades of coastal Orange County market experience to every client relationship. He is a proud member of the California Association of Realtors, the National Association of Realtors, and the Laguna Board of Realtors. CA DRE # 01379585.
Coldwell Banker Realty · (949) 246-8500
Equal Housing Opportunity. Ron Pickett, CA DRE # 01379585, Coldwell Banker Realty CA DRE # 00616212, regulated by the California Department of Real Estate. This article is general information only and does not constitute legal, tax, or financial advice. Confirm your specific numbers with your escrow officer, tax advisor, or lender.