Book showings only after a lender has reviewed your income, assets, debts, and credit and issued a documented pre-approval. Then ask what conditions are still open, set a touring ceiling below your maximum approval, and confirm the letter's expiration date so you can act when the right home appears.
What should first-time buyers have ready before touring Orange County homes?
Before touring Orange County homes, get a lender to review your income, assets, debts, and credit and issue a documented pre-approval, not just a quick prequalification. Have your pay documents, bank statements, and credit information ready, then ask the lender which conditions are still open. Set your touring ceiling below your maximum approval so the monthly payment, taxes, insurance, and cash reserves still fit your life.
Key Takeaways
Recent local market data shows median sale prices from $972,500 in Aliso Viejo to $2,077,500 in Dana Point across seven Orange County areas, so the same approval amount stretches very differently from city to city.
A pre-approval letter rests on a lender's review of documents such as W-2s, bank statements, and credit, which makes it more substantive than an informal estimate of what you can afford.
Your lender's maximum loan amount is not your comfortable budget, because taxes, insurance, HOA dues, maintenance, and reserves all sit outside that number.
A pre-approval can still carry conditions such as income and asset verification, appraisal, title review, and insurance, so ask for them in writing before you treat the letter as offer-ready.
Letters can expire, so confirm the validity date and ask when your lender will need updated pay, asset, credit, or employment documents.
I've spent years on both sides of this process, first in mortgage lending and now as a Realtor, and the pattern with first-time buyers is consistent. The ones who get the most out of touring Orange County homes are the ones who did the lender work first. My rule is that the lender conversation comes before the showing calendar, not after you fall for a house.
Why does a documented pre-approval matter before touring Orange County homes?
A documented pre-approval tells you a realistic price range and lets you move quickly when a suitable home appears. A prequalification is usually a fast estimate based on numbers you report yourself, and it isn't offer-ready financing.
Prequalification versus pre-approval
The California Department of Real Estate explains that a pre-approval letter is based on a lender's review of your financial information and documents, including items such as W-2s, bank statements, and credit score. That's a different animal from plugging numbers into an online calculator. The California Department of Financial Protection and Innovation also advises first-time buyers to get a mortgage pre-approval that specifies how much a lender is willing to lend.
If you're curious why I push the lender conversation so hard, I laid out the reasoning in 3 huge reasons to talk to a mortgage lender before you start house-hunting.
Why speed matters in this market
Across the wider Laguna Beach, CA market, recent local market data shows 146 homes for sale now and 80 homes sold over roughly the last 90 days as of November 2026. That's area-wide context, not a price expectation for any one home, but it shows the market moves. When a home that fits your budget and your list shows up, you want financing that's already been reviewed.
What should be in your lender file before you book showings?
Your lender file should include the documents your lender asks for, organized and ready, plus a clear answer to what remains conditional on your approval. The exact list varies by lender and loan type, so confirm yours before you start gathering.
The documents to gather
Beyond the W-2s, bank statements, and credit information the DRE names, a practical file often includes:
Recent pay documentation for every borrower on the loan
Federal tax returns, when your lender requests them
Statements for investment or retirement accounts you plan to count toward funds or reserves
Documentation of gift funds, if a relative is helping with the down payment
Written explanations for unusual deposits or credit events
If you're using a VA loan or another government-backed product, ask your lender for that program's specific documentation list. Don't assume a conventional checklist covers it.
What to ask your lender about conditions
A pre-approval may still depend on verification of income and assets, the appraisal, title review, property eligibility, insurance, or other underwriting conditions. Before you treat the letter as offer-ready, ask your lender for:
The approved loan amount and loan type
The down payment amount the approval assumes
The validity or expiration date
Your rate-lock status
A list of any outstanding conditions
Timeline questions come up constantly, and I won't hand you a number that doesn't apply to you. How long a pre-approval takes depends on your lender and how quickly you supply complete documents. Ask your lender for a realistic turnaround before you plan your first showing.
Program rules are not universal rules
If you're exploring down payment assistance, know that program rules differ from general mortgage practice. CalHFA's 2026 materials, for example, require an approved lender to complete a pre-approval letter for applicable assistance programs. Its guidance also warns that original pre-approval letters may expire, so eligibility should be confirmed before you shop.
The California Dream For All lender form lists the factors an approved lender evaluates, including your application, credit report, income, first-time-buyer status, first-generation status, and automated-underwriting findings. That form is specific to that program. Likewise, CalHFA's definition of a first-time buyer, someone without an ownership interest in a principal residence in the previous three years, applies to its program context. A conventional, FHA, or VA lender may define it differently, so ask.
How do you set a touring price range that fits Orange County?
Set your touring ceiling below your lender's maximum approval, based on the monthly cost you're comfortable carrying. The maximum loan amount tells you what a lender will approve, not what fits your life.
Build the real monthly picture
Beyond the mortgage payment, account for property taxes, homeowners insurance, HOA dues where applicable, maintenance, utilities, and cash reserves. Your lender can confirm which of those items it included in your qualification calculation. Anything it left out is yours to budget.
Cash needs go beyond the down payment too. Plan for closing costs, inspection and appraisal-related expenses, moving, and a reserve cushion. I'll walk you through how those categories apply to your purchase and your loan type in a consultation, because the right answer depends on your specifics.
Know how prices vary by area
Here's how recent local market data compares across several of the areas I work in. These are area-level medians, and an individual home's value depends on condition, street, build year, and timing.
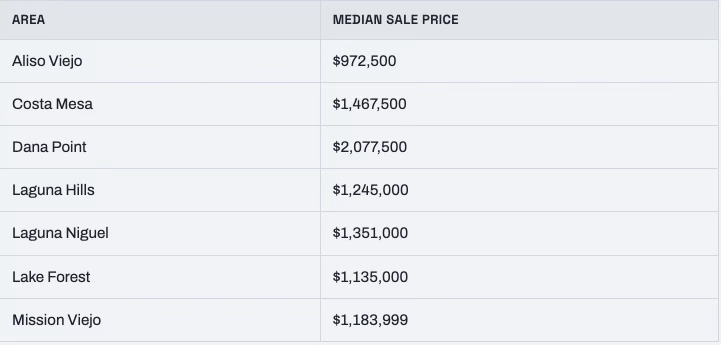
Comparison of median home sale prices across seven Orange County cities, including Aliso Viejo, Costa Mesa, Dana Point, Laguna Hills, Laguna Niguel, Lake Forest, and Mission Viejo, based on trailing 90-day market data as of November 2026.
Source: aggregated public listing data, trailing 90 days, as of November 2026.
The spread is wide. Across the wider Laguna Beach, CA market, the median sale price for homes sold over roughly the last 90 days was $3,285,000. That's area-wide context, and it shows why the same pre-approval amount can mean a very different home depending on the city. Your touring list should reflect your approval and your comfortable budget together, not just one of them.
If you're considering buying along the coast, explore Dana Point homes for sale and local real estate trends to get a better understanding of available properties and the local market.
For broader county trends, Orange County REALTORS® publishes a monthly Orange County market report worth reading alongside your lender conversation.
Recheck the letter while you search
Even outside CalHFA programs, ask your lender when updated income, asset, credit, or employment documentation will be required. A new credit card, a job change, or a big deposit mid-search can change what your lender needs to see. Tell your lender before you make a move, not after.
Once your file is in place, this 5-step checklist for first-time buyers is a good next read. When you start walking homes, review the top 5 things buyers forget to check during a viewing and home viewing etiquette.
FAQ
Do I need a mortgage pre-approval before touring homes in Orange County?
You're not legally required to have one, but I strongly recommend it. A documented pre-approval sets a realistic price range before you fall for a home you can't finance, and it prepares you to make an offer when the right one appears.
What is the difference between prequalification and pre-approval?
A prequalification is typically a quick estimate based on information you report. A pre-approval involves a lender reviewing your actual documents, such as W-2s, bank statements, and credit, which makes it far more useful when you're ready to make offers.
What documents should I gather before applying?
Start with recent pay documentation, bank statements, and credit information, then add tax returns, retirement or investment statements, gift-fund documentation, and explanations for unusual deposits if your lender asks. The exact list varies by lender and loan type, so confirm it before you start.
How long does a mortgage pre-approval last?
It depends on your lender, so check the validity or expiration date on your letter. Some programs, like CalHFA's, specifically warn that original letters may expire, and your lender may ask for updated documents during a long search.
Does a pre-approval guarantee my mortgage will be approved?
No. A pre-approval can still depend on verification of income and assets, the appraisal, title review, property eligibility, insurance, or other underwriting conditions. Ask your lender which conditions remain open on your letter.
Getting your financing reviewed first is what turns touring Orange County homes from browsing into a plan. I can connect you with the right questions to ask, help you set a touring ceiling that fits your budget, and walk you through homes in Dana Point, Laguna Beach, Mission Viejo, and the rest of the county. When you're ready, get a free home valuation or search coastal listings with me, and we'll start with a consultation about your numbers.
About Ronald “Ron” Pickett
Ron Pickett is an Orange County luxury Realtor and Dana Point and coastal property expert, verified in the Top 1.5% nationwide by RealTrends (2023, 2025 and 2026). A retired firefighter and USMC veteran who began in mortgage lending in 2003, he has lived in Orange County since 1993 and now helps buyers, sellers, and investors across the county from his home base in Dana Point.
Coldwell Banker Realty · (949) 246-8500
Equal Housing Opportunity. Ron Pickett, CA DRE # 01379585; Coldwell Banker Realty, CA DRE # 00616212. Regulated by the California Department of Real Estate. This article is general information, not legal, tax, or financial advice; confirm your own numbers with your escrow officer, tax advisor, or lender.