Before you trust a rent number, verify four things on the specific property: whether the rent holds against recently leased comparables, what vacancy and repairs will actually cost, what a real insurance quote looks like, and whether your intended use is permitted, especially short-term. Then rerun the deal at a lower rent.
How should Newport Beach investors evaluate rent potential beyond the purchase price?
Newport Beach investors should treat projected rent as one assumption to test, not a guarantee. Compare it with recently leased comparables, then subtract realistic vacancy, turnover costs, maintenance reserves, an insurance quote for the actual address, and any city permit requirements if you're considering short-term use. If the deal only works at the optimistic rent, it doesn't work.
Key Takeaways
Recent local market data (roughly the last 90 days) shows a median sale price of $3,895,000 across the wider Newport Beach, CA market, so a small miss on rent matters against a large purchase basis.
Northmarq reported Orange County multifamily average asking rent of $2,670 per month in Q3 2026, up 0.6% year over year, with 4.6% vacancy, which is a countywide benchmark and not a forecast for your property.
Colliers reported Orange County average effective rent of $2,743 per unit in Q2 2026, and effective rent can treat concessions differently than advertised asking rent.
The City of Newport Beach states that the maximum number of active short-term lodging permits is 1,550, so short-term eligibility is a feasibility question for each address.
Insurance, condition, and reserves are property-specific, so get a real quote and a real inspection before you underwrite income.
What rent can a Newport Beach property realistically achieve?
A realistic rent comes from recently leased comparables that match your unit type, size, location, and condition, not from a countywide average or an online estimate. Countywide numbers are a starting benchmark and nothing more.
When I sit down with Newport Beach investors, the first thing I do is separate three numbers that people blur together: what a unit is advertised at, what it effectively rents for after concessions, and what similar places actually leased for. Those can be three different figures.
What do the countywide benchmarks actually tell you?
They tell you the direction of the Orange County apartment market, and they disagree with each other because the providers measure different things. Here are two of the latest published figures:
Orange County Rental Market Benchmarks - Q2-Q3 2026
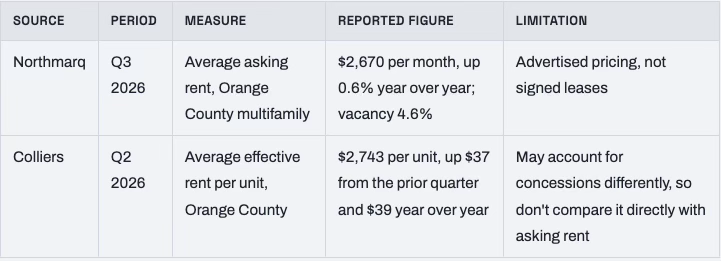
Orange County rental market benchmarks comparing Northmarq Q3 2026 asking rent and vacancy data with Colliers Q2 2026 effective rent data, including each source’s limitations.
Neither report is a Newport Beach forecast. Unit size, parking, views, distance to the coast, building amenities, furnishing, and whether you're comparing apartments, condos, or single-family homes can move a property well away from a countywide average. New apartment deliveries also add competing supply, so look at the specific submarket around your property.
Pull recently leased units, not just current listings. Record concessions, lease length, included utilities, parking, and furnishings for each comparable, because the same headline rent can mean very different income.
What costs and risks sit between projected rent and your actual return?
Vacancy, turnover, deferred maintenance, insurance, and management or association costs all come out of projected rent before you see a dollar. Each one needs its own line in your analysis.
How should you model vacancy and turnover?
Model them separately, using the specific property and its comparables. A low countywide vacancy rate doesn't guarantee your unit leases quickly at your number.
Build in downtime between tenants, cleaning, repainting, marketing, leasing costs, and any utilities or services you pay as the owner. Then ask what a delayed lease-up does to your first year.
What should you inspect before counting the rent as income?
Inspect for the problems that coastal properties tend to hide, and set your reserves from what you find. In coastal Newport Beach, I want a close look at:
Moisture intrusion and corrosion
Roofing, windows, and doors
HVAC, plumbing, and electrical systems
Balconies, decks, and drainage
Common areas and association obligations if it's a condo or townhome
Big-ticket systems like HVAC aren't just a line in your reserve budget. When the inspection report comes back, they're also some of your strongest negotiating points on price. The right reserve depends on the property's age, construction, maintenance history, and what the inspection finds.
How much does insurance change the math?
Enough that you should never apply a generic percentage to rent. Get an actual quote for the address and the coverage type before you finalize your numbers.
Confirm that the policy covers your intended rental use, loss of rents, and liability. Also check how it treats water damage and other coastal exposures, and read the exclusions and deductibles. For a condominium, separate the owner's policy from the association's master policy, and review the governing documents to see who is responsible for what. Your lender and insurance agent can walk you through your specific coverage questions.
What other operating expenses belong in the model?
Include property management, repairs and maintenance, association dues if any, property taxes, owner-paid utilities, and your reserves. I'd rather you overestimate expenses and be pleasantly surprised than the other way around. Ask your tax advisor how rental income and these expenses will be treated for you.
Can you count short-term rental income in Newport Beach?
Only if the specific property qualifies, and you shouldn't value the deal on short-term income until you've confirmed that. The City of Newport Beach defines short-term lodging as renting a residential unit for 30 consecutive days or less, and the definition includes home sharing.
What does the city require?
Per the city's short-term rental information page, short-term lodging is allowed only in specified residential zones, including R-1.5, R-2, and RM, and it requires both a short-term lodging permit and a business license. The city also states a cap of 1,550 active permits, so whether a permit is available for your address is a feasibility question, not a pricing question.
Permit holders also pay a 10% transient occupancy tax on the lease amount, according to the city's short-term rental rules. Permits come with ongoing administrative obligations too. The city's 2026 renewal submission deadline was October 31, 2026, and it posts updates on its short-term lodging notices page. If you're evaluating a property that already holds a permit, confirm its status and what the city requires for the next cycle. Also check any association restrictions, since the city's rules aren't the only ones that can apply.
How do short-term and long-term models differ?
They have different revenue and cost structures, so you can't swap one rent figure for the other. A short-term model has to account for:
Platform or management charges
Furnishing, utilities, cleaning, and supplies
Vacancy between bookings
Transient occupancy tax, permit, and business-license requirements
Compliance risk if rules change or aren't followed
A long-term model generally has different turnover, furnishing, utility, and management assumptions. Underwrite each strategy on its own merits and compare the results.
How should Newport Beach Investors stress-test a rental deal?
Change one assumption at a time and see whether the deal still works. The question isn't whether the rent estimate is plausible. It's whether the investment survives if the rent turns out to be lower than advertised.
Recent local market data shows a median sale price of $3,895,000 across the wider Newport Beach, CA market, based on homes sold over roughly the last 90 days, with a median of 28 days from listing to contract and 338 homes for sale now. That's area-wide context only. An individual property's value depends on condition, street, build year, and timing, and your analysis should rest on the specific address. When the price basis is that large, a modest rent shortfall or an unexpected repair carries real weight.
Newport Beach Rental Investment Stress Test
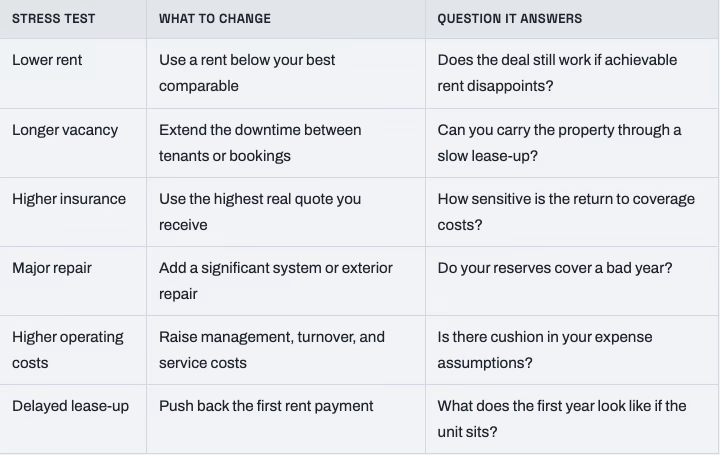
Newport Beach rental investment stress test showing how lower rent, longer vacancy, higher insurance, major repairs, higher operating costs, and delayed lease-up can affect an investment decision.
If the property only works in the best case, adjust your offer or walk. Once your numbers hold up, my questions to ask before making an offer will help you decide what to put on the table. It's also worth understanding how nearby properties can affect a home's value, because the surrounding blocks affect both rent and resale.
I've bought investment properties in Newport Beach myself, and I can tell you the deals that disappoint are almost always the ones where nobody tested the assumptions.
FAQ
What rent could this Newport Beach property realistically achieve today?
Start with recently leased comparables that match the property's unit type, size, condition, and location. Countywide figures, such as Northmarq's Q3 2026 average asking rent of $2,670 per month, are only a benchmark. Your number should reflect concessions, parking, utilities, and furnishings, and I can help you pull comparables for a specific address.
How do I compare long-term rent with short-term lodging income in Newport Beach?
Underwrite each strategy separately, with its own revenue and its own costs. Short-term income has to absorb cleaning, furnishing, platform or management charges, vacancy between bookings, and a 10% transient occupancy tax for permit holders. Before any of that matters, confirm the property is eligible for a permit at all.
What operating expenses should I include when evaluating a Newport Beach rental?
Include property taxes, insurance, management, repairs and maintenance, association dues if applicable, owner-paid utilities, turnover costs, and a reserve for major systems. Get real quotes and inspection findings rather than rules of thumb. Your tax advisor can tell you how these expenses affect your situation.
How much vacancy and turnover should I assume for an Orange County investment property?
Base it on the specific property and its comparables, not on a countywide figure. Northmarq's 4.6% Q3 2026 vacancy is a reference point, but it doesn't tell you how fast your unit will lease at your rent. Model vacancy and turnover costs as separate lines, including cleaning, paint, marketing, and leasing.
Does the property's zoning allow short-term rentals or home sharing?
It depends on the parcel. The City of Newport Beach says short-term lodging is allowed only in specified residential zones, including R-1.5, R-2, and RM, and requires a permit and a business license. See the city's short-term rental page and confirm the parcel's zoning, permit availability, and any association restrictions before you rely on that income.
Projected rent is an input, not income. The investors who do well in this market test the number against comparables, inspection findings, real insurance quotes, and the city's rules before they write an offer. If you want to run that analysis on a specific property, I'll walk through it with you. Search coastal listings or request a free home valuation, and let's book a consultation.
About Ron Pickett
Ronald “Ron” Pickett is an Orange County luxury Realtor and Dana Point and coastal property expert, verified in the Top 1.5% nationwide by RealTrends (2023, 2025 and 2026). A retired firefighter and USMC veteran who spent nine years at MCAS El Toro, Ron built a background in mortgage lending and investing in Newport Beach and surrounding areas before focusing on helping buyers, sellers, and investors across Orange County. He has lived in the county since 1993 and resides in Dana Point.
Coldwell Banker Realty · (949) 246-8500
Equal Housing Opportunity. Ron Pickett, CA DRE # 01379585; Coldwell Banker Realty, CA DRE # 00616212. Regulated by the California Department of Real Estate. This article is general information, not legal, tax, or financial advice; confirm your own numbers with your escrow officer, tax advisor, or lender.